How to Prevent Loan Servicing Complaint Benchmarks: Features Your LMS Must Have
Bob Schulte
Aug 4, 2026
9 mins read
*Curated as per Consumer Financial Protection Bureau (CFPB) Complaint Benchmarks for Loan Servicing Operations
 BrytSoftware
Loan Servicing Complaint Benchmarks
Loan servicing complaint benchmarks measure the volume and category of formal borrower complaints filed with the Consumer Financial Protection Bureau (CFPB). The database is publicly searchable by company name, product type, and issue category.
Two facts define your exposure.
1. The complaint is on your public record before your response is. The CFPB logs every complaint the moment a borrower files. Your organization appears in the database while the complaint is still open. Borrowers only need to file, not prove. Future borrowers, investors, auditors, and regulators can query that record at any time.
2. You have 15 days to respond in writing. That window starts the day the complaint is filed. If your LMS does not give you immediate access to the full loan record, payment history, notice log, and fee data, your response will be incomplete. An incomplete response on a public platform adds to your complaint count.
Each category below is a public data point the CFPB already holds about your organization. Here is what is driving it and what your Loan Management Software (LMS) must do differently.
In 2025, the CFPB received 6.6 million complaints – double the 2024 volume. All five categories below recorded higher complaint volumes, with unexpected fees for personal loans up 82%, payday loans up 89%, and inaccurate credit reporting up 249% (CFPB Consumer Response Annual Report, March 2026). [Source]
Payment misapplication corrupts delinquency records when the waterfall runs on a manual override rather than a system-enforced rule. Review payment waterfall mistakes that corrupt delinquency reports as the baseline diagnostic.
Your LMS must apply a fixed payment hierarchy to every payment without servicer intervention.
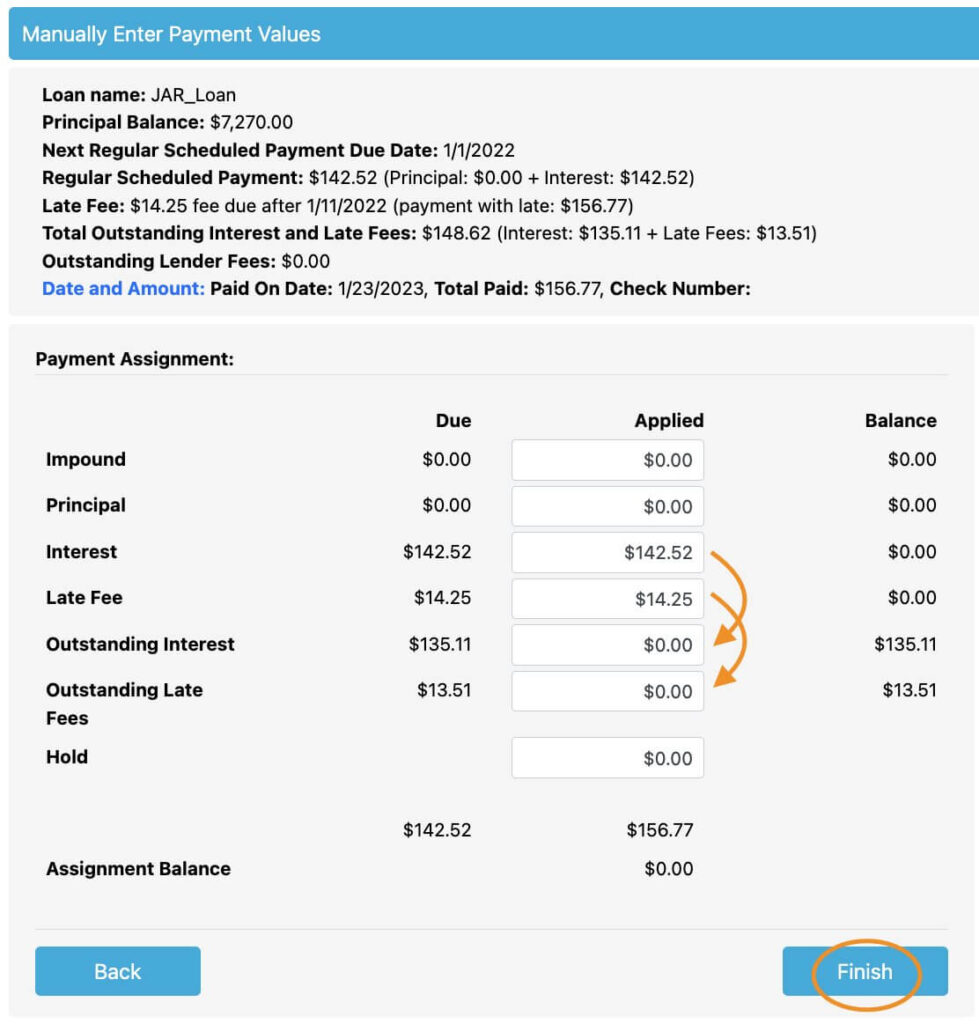
In Bryt, Payment Waterfall Rules enforce a configurable payment sequence (impound, lender fees, interest, late fees, outstanding balances, then principal) on every payment posted, with the full allocation logged on the loan schedule.
Unexpected fees represent 22% of all personal loan complaints (CFPB Consumer Response Annual Report 2023). The servicer cannot produce a pre-dated disclosure tied to the specific loan. A non-sufficient funds (NSF) fee applied without a pre-configured fee type is the most common single-complaint trigger for payday and consumer lenders. Review what mishandled NSF events cost payday lenders.
Your LMS must lock fee types to the loan record at setup, not at the time of application.
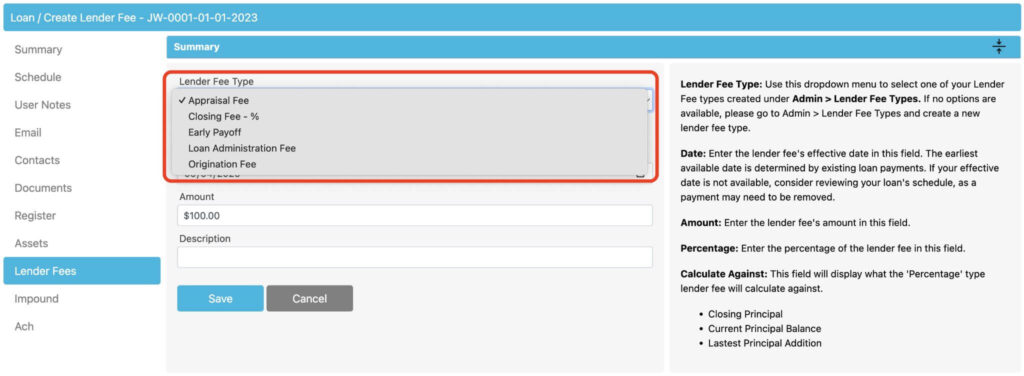
In Bryt, the Lender Fees module creates fee types (NSF, origination, closing cost, recurring) with defined amounts applied at each triggering event and logged to the loan record.
Notice failures occur when a borrower files a notice stating they received no communication about a payment change, balance update, or default action. ACH payment failures carry separate notice obligations that compound when untracked. Review how to handle failed ACH payments before your next compliance review.
Your LMS must record every late payment notice sent, queued, and failed, attached to the specific loan.

In Bryt, the Notices module logs every sent, queued, and failed notice on the Notice Dashboard, with each record attached to the individual loan file and borrower file.
Payoff disputes spike when the quoted amount does not match the final collection. Manual calculations introduce per diem errors, rate change miscalculations, and outstanding fee omissions.
Your LMS must calculate payoffs from live loan data for a selected payoff date, with outstanding interest and fee balances itemized. Review payoff quotes and statements for private lenders as the baseline reference.

In Bryt, the Payoff Calculator generates a payoff figure from live loan data for a selected date, itemizing outstanding interest, existing late fees, and outstanding lender fee balances by period.
Education lender complaints reached 22,900 in 2024-25 – the highest volume ever recorded with modification documentation failures as the primary driver (CFPB Private Education Loan Ombudsman Annual Report 2025). A loan modification logged in an email chain and not in the servicing system does not exist for audit purposes.
Your LMS must record every term change (rate, amortization, principal, extension, due date) with an effective date tied to the loan record.
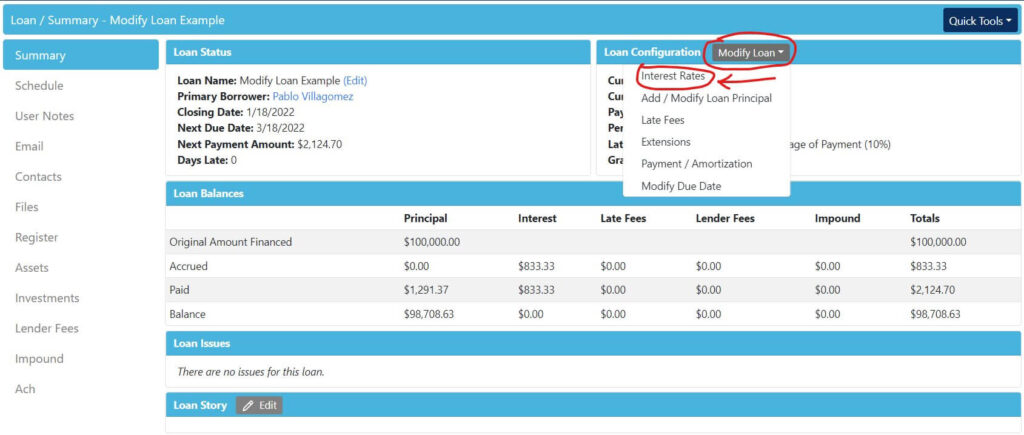
In Bryt, the Loan Modification module records interest rate changes, amortization adjustments, principal modifications, and due date changes with effective dates reflected on the loan schedule.
Complaint exposure is vertical-specific. Using an industry-wide benchmark to manage compliance for a single-vertical portfolio means measuring the wrong risk.
*Take the risk assessment score above & get the compliance checklist personalized to your lending vertical.
J.D. Power’s 2026 U.S. Mortgage Servicer Satisfaction Study puts overall servicer satisfaction at 607 out of 1,000, up 11 points from last year’s all-time low. Satisfaction recovered slightly, but 30% of borrowers now believe they are at risk of foreclosure, up from 17% four years ago, and only 41% are classified as financially healthy. [Source]
Consumer lenders, payday lenders, and neobanks carry the highest fee complaint volumes. Delinquency tracking failures upstream compound fee disputes downstream. Review best practices to prevent loan delinquency from turning into default alongside your fee disclosure review.
Your LMS must lock fee schedules at loan setup and track delinquency by period.
In Bryt, the Lender Fees module locks fee schedules to the loan record, and the Loan Register logs every fee event with a date and account type.
Private and commercial lenders face the highest rate of payoff disputes and trust fund discrepancies. Review late fee logic for private lenders as the adjacent gap — late fee misconfiguration feeds directly into payoff calculation errors.
Your LMS must generate payoffs from live data and apply late fees through a configurable rule.
In Bryt, the Payoff Calculator pulls live loan data for the selected payoff date, and late fee configurations are managed through the Loan Modification module’s late fee settings.
Education lenders and CDFIs face the sharpest complaint growth in 2024-25, driven by modification documentation failures and missing notice records.
Your LMS must log every term change with an effective date and every notice with a delivery record, both tied to the loan file.
In Bryt, the Loan Modification module records term changes with effective dates on the loan schedule, and the Notices module logs every notice to the loan file and borrower file.
The CFPB uses complaint volume and category concentration to prioritize which non-bank lenders it selects for supervisory examination. A 2025 analysis from Vergent LMS confirms that agencies used complaint data directly to steer examination schedules for non-bank servicers. Goodwin’s 2025 Consumer Financial Services Year in Review tracked 13 mortgage origination and servicing enforcement actions in 2024, recovering approximately $43 million.
Lenders who treat complaints as a customer service issue, rather than a regulatory exposure metric, are measuring the wrong risk.
A complete, date-stamped record of every payment, notice, fee, and modification is the only foundation for a 15-day CFPB response. That record must be retrievable by loan, borrower, and date without manual reconstruction. Review the month-end loan servicing checklist as the operational baseline.
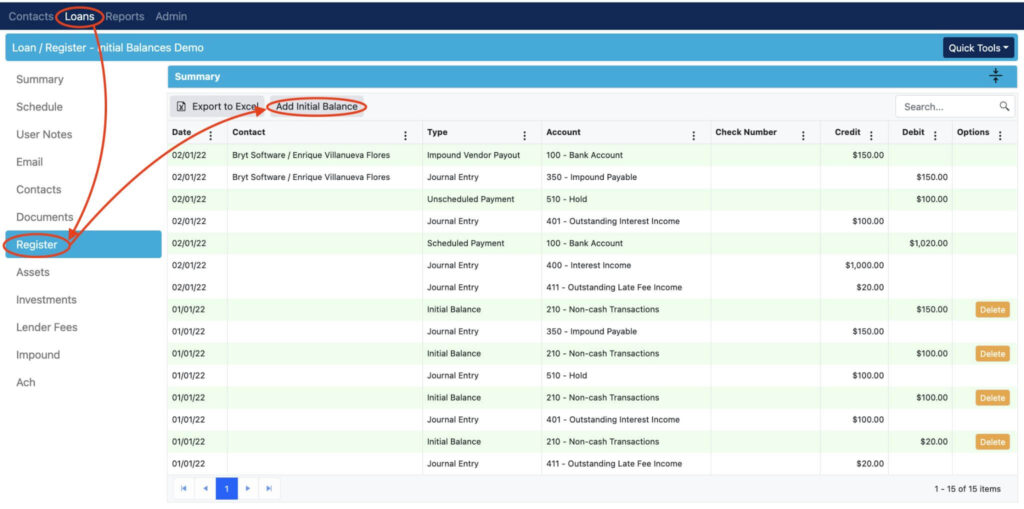
In Bryt, the Loan Register shows every transaction by date, type, account, and credit/debit amount at the loan level, available for compliance review without manual file reconstruction.
A servicer who cannot locate the full loan record within the response window defaults to non-response. Regulators treat non-response as confirmation of the complaint. Review non-compliance implications in the lending industry for the full enforcement picture. Your LMS must surface payment history, notice log, fee record, and modification history in a single view without switching screens.

In Bryt, the Loan Summary gives servicers access to the payment schedule, lender fee history, and notice log for a specific loan in one view.
The servicers who stay off the priority examination list close the five gaps above at the platform level before the first complaint reaches a regulator.
Bryt Software is built for post-origination loan servicing across private lenders, consumer lenders, CDFIs, commercial lenders, and all the other verticals covered in this post.
Every gap in this post is already producing public complaints across your vertical. Book a demo walkthrough, and I will show you exactly which ones your current LMS is leaving open.
© 2026 Bryt Software LLC. All Rights Reserved.